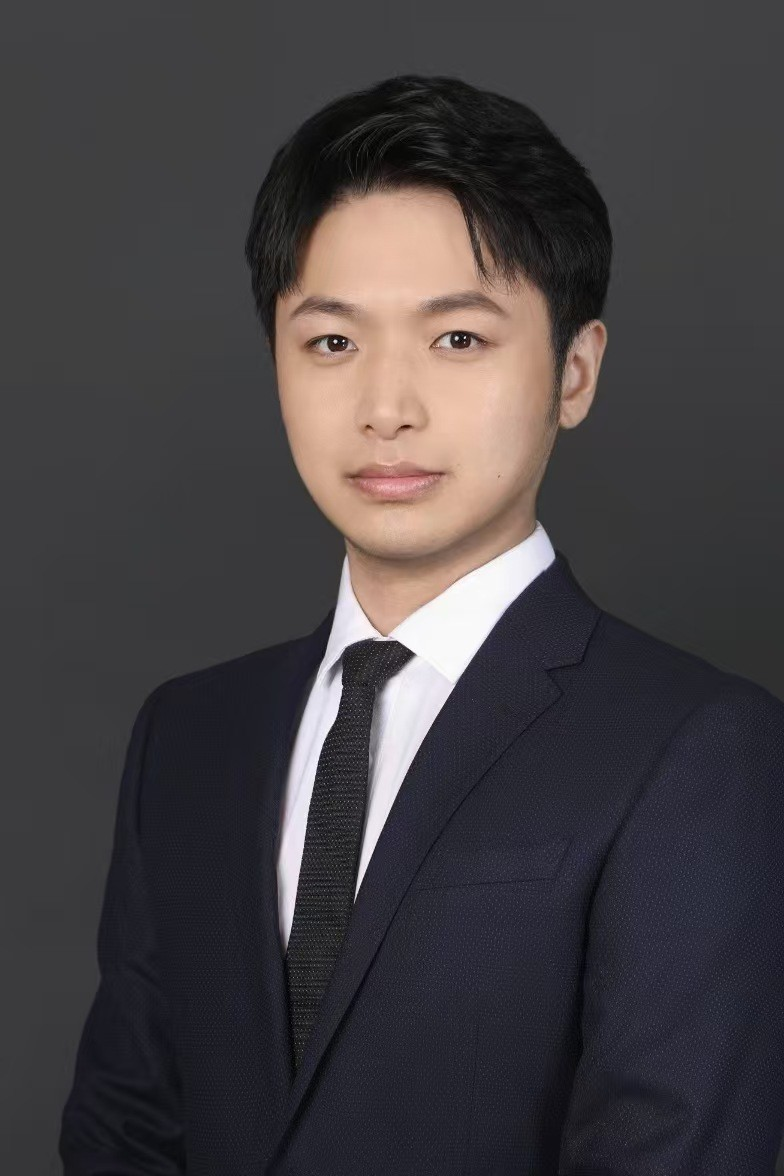
报告人: 张大可(上海交通大学)
时间:2026-11-12 13:30-14:50
地点:Room 217, Guanghua Building 2
Abstract:
In economic forecasting, principal component analysis (PCA) has been the most prevalent approach to the recovery of factors, which summarize information in a large set of predictors. Nevertheless, the theoretical justification of this approach often relies on a convenient and critical assumption that factors are pervasive. To incorporate information from weaker factors, we propose a new prediction procedure based on supervised PCA, which iterates over selection, PCA, and projection. The selection step finds a subset of predictors most correlated with the prediction target, whereas the projection step permits multiple weak factors of distinct strength. We justify our procedure in an asymptotic scheme where both the sample size and the cross-sectional dimension increase at potentially different rates. Our empirical analysis highlights the role of weak factors in predicting inflation, industrial production growth, and changes in unemployment.
About the Speaker:
Dake Zhang received his Ph.D. in Econometrics and Statistics and an MBA from the University of Chicago Booth School of Business. He also holds a Bachelor's degree in Mathematics from Tsinghua University and a Master's degree in Statistics from the University of Chicago.
His main research areas are statistical and machine learning methods and their applications in finance. His research has been accepted by leading journals and conferences, including the Journal of Finance (JF), the Journal of the American Statistical Association (JASA), the International Conference on Machine Learning (ICML), and the International Conference on Learning Representations (ICLR).
Your participation is warmly welcomed!
欢迎扫码关注北大统计科学中心公众号,了解更多讲座信息!