报告人: 孔新兵(东南大学)
时间:2026-11-19 09:00-10:30
地点:Room 217, Guanghua Building 2
Abstract:
In this talk, we introduce a conditional asset pricing transformer (CAP-T) that captures nonlinear interactions among firms through attention to forecast excess returns. In the first stage, a transformer estimates conditional expected returns, and kernel-weighted principal component analysis of its residuals estimates the local factor loading space. Projecting the conditional mean onto this space separates aggregate factor risk compensation from conditional mispricing. Then, in the second stage, separate transformers learn these two components, whose predictions are combined to forecast returns. As a result, the proposed framework decomposes returns into conditional mispricing, aggregate factor risk compensation, a centered factor component, and an unpredictable innovation. We establish approximation and generalization bounds and characterize how first-stage prediction errors propagate through local factor estimation and component learning, providing statistical guarantees for conditional mispricing, factor loadings, and factor risk premia. Finally, simulations and empirical studies demonstrate the predictive and interpretive benefits of the proposed method.
About the Speaker:
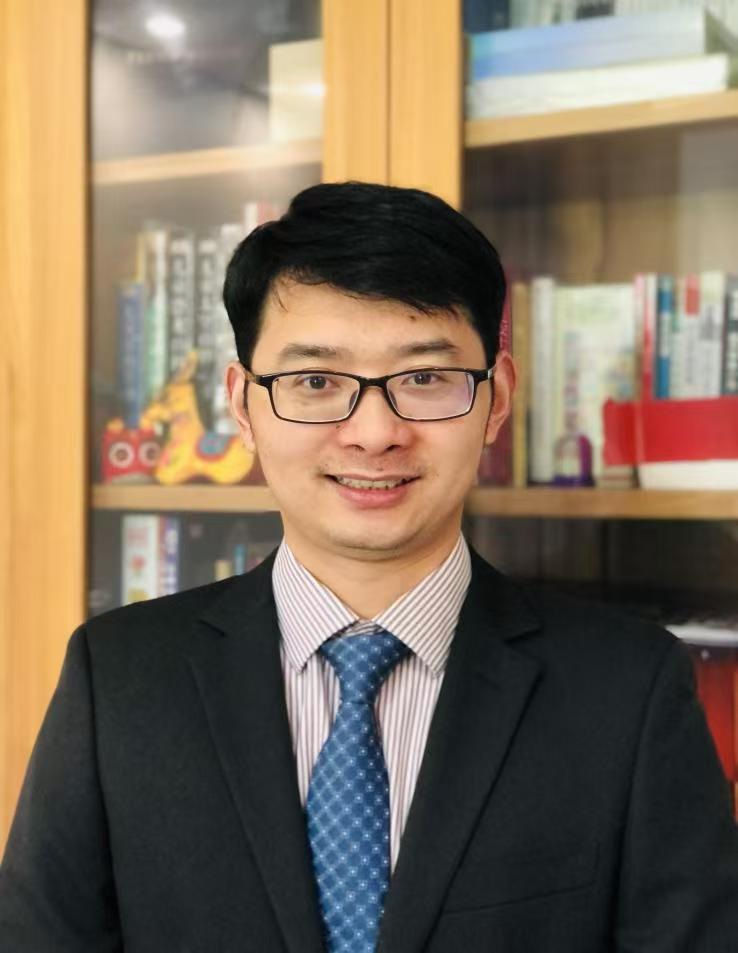
东南大学统计与数据科学学院教授、副院长。主要研究兴趣为高频和高维计量经济学、生成式人工智能、数据科学及其应用;在统计学四大刊 AoS、JASA、Biometrika 和计量经济学顶刊 JoE、JBES 发表论文20余篇;主持国家自然科学基金重点专项等项目课题5项;主持完成或正在承担中钢集团CAD对象识别和自动算量系统开发、招商银行南京分行大模型应用、马上消费金融服务有限公司智能体开发、江苏中源售电有限公司电力交易预测等多个企业项目。获第一届统计科学技术进步奖一等奖、教育部优秀科技成果奖(人文社科)等奖项。江苏省教育系统先进个人(优秀教师),参编统计学101教材《统计机器学习》。担任计量经济学期刊 JBES 副主编、统计学习和数据科学期刊 SLADS 副主编。现为国际统计学会当选会员(ISI elected member),江苏概率统计学会理事长,中国现场统计研究会多元分析应用专业委员会副理事长。
Your participation is warmly welcomed!
欢迎扫码关注北大统计科学中心公众号,了解更多讲座信息!